May 15, 2026
Limited Matching & Cosmetic Damage Exclusions (What They Mean for Your Claim)
Latest Post
Hurricane Isaias Property Damage: Next Steps for Your Claim
October 13, 2026
What Happens After an Insurance Claim Denial? A Step-by-Step Guide for Policyholders.
September 13, 2026
Resolve Before Litigation: Demand Letters, Notices of Intent, Mediation, and Appraisal in Insurance Disputes
September 13, 2026
After a storm damages part of your roof, siding, or exterior, you might expect your insurance company to restore the property to its pre-loss condition. What some policyholders receive instead is payment covering only the damaged section — leaving an obvious mismatch between the repaired area and the rest of the structure.
Two policy provisions drive this outcome: limited matching exclusions and cosmetic damage exclusions. Each restricts the scope of what an insurer will pay for. Each generates disputes. Understanding how they work is the first step toward evaluating whether the coverage position you’ve received is correct.
If your claim has been paid at a level that doesn’t reflect the actual scope of your loss, contact Kandell, Kandell & Petrie at (305) 858-2220 to discuss your situation.
What Is a “Matching” Issue?
A matching issue arises when a covered loss damages only a portion of a larger continuous surface — roof shingles, siding panels, flooring — and the materials needed for repair don’t match the undamaged areas.
Shingles and siding panels are manufactured in batches. Colors and textures shift between production runs. Materials fade and weather with exposure. When a storm damages one section of a ten-year-old roof, finding materials that match the undamaged sections may not be possible. The repair may be structurally sound, but the visual result is a patchwork.
Common scenarios include:
- Roof shingles: A matching roof shingles exclusion limits the insurer’s obligation to cover replacement of undamaged slopes, even when an exact match is unavailable.
- Siding panels: A siding matching exclusion prevents the carrier from being required to replace panels on adjacent walls when the original color or profile has been discontinued.
- Interior surfaces: Where a continuous surface is partially damaged, replacement materials may not match the undamaged sections in tone, texture, or finish.
What Is a Limited Matching Exclusion?
A limited matching exclusion is a policy provision or endorsement that restricts — or eliminates — the insurer’s obligation to pay for repairs in adjoining undamaged areas to achieve a uniform appearance.
Matching exclusion insurance disputes typically turn on the exact policy language, the applicable state’s regulatory framework, and the specific facts of the claim.
What Is a Cosmetic Damage Exclusion?
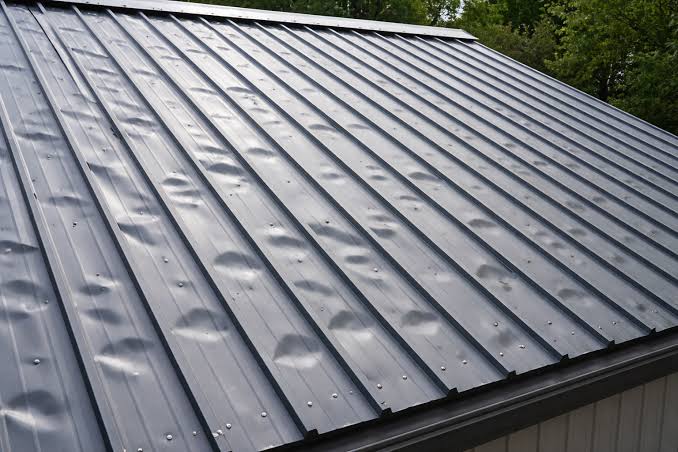
A cosmetic damage exclusion eliminates coverage for damage that affects a property’s appearance without impairing its ability to perform a protective function. If hail leaves visible dents on a metal roof that still seals out weather, the insurer may characterize that damage as cosmetic and decline to pay for repairs.
Cosmetic damage exclusions appear most often in hail damage and wind damage claims.
Common applications include:
- Dented metal roofing: Hail impact creates visible dents or dimples that don’t compromise the roof’s weatherproofing capacity.
- Impact-marked siding: Debris leaves visible marks on siding that remains structurally intact and protective.
- Pitted or marred surfaces: Roofing, gutters, and flashing that show surface damage without structural compromise.
Whether damage is only cosmetic depends on the roofing system, the policy definition, and what a qualified inspection shows. Granule loss, dents, fractures, or coating damage may matter, but any effect on function or remaining service life should be supported by the inspection findings.
How These Exclusions Affect Payouts
Each type of exclusion narrows the scope of loss the insurer will recognize. A claim that otherwise supports full roof replacement may be paid as a partial repair. A siding claim that reasonably requires replacing an entire elevation may be resolved at one wall section.
The result is not necessarily a flat denial. It is often an underpaid claim — a settlement that covers part of the loss while leaving the property with visible inconsistencies, reduced useful life, and a payout that doesn’t reflect the cost of genuine restoration. Scope-of-loss disputes of this kind are among the more contested areas of property insurance litigation.
What to Look for in the Insurer’s Letter
Start with the exact endorsement or exclusion the insurer cites. Then compare it with the repair estimate and inspection report. Look for three separate questions: what damage the insurer accepted, what repair it approved, and what part of the requested work it says is excluded. Keeping those questions separate often makes the disagreement easier to understand.
When Matching and Cosmetic Disputes Become Negotiable
The insurer’s position at the adjustment stage is not the final word. Several factors can shift the analysis.
Detailed photographic documentation of the damage, the condition of undamaged areas, and the visible mismatch after repair provides a factual record that supports a broader scope of loss. An independent contractor or engineer’s report can establish whether damage characterized as cosmetic has measurable functional consequences, and can provide a credible estimate of the full repair cost.
The appraisal clause is worth evaluating where the dispute concerns the amount of the loss rather than whether coverage applies. Appraisal addresses valuation (what a covered loss is worth) and can resolve scope disputes without litigation. If the insurer’s position is that the exclusion eliminates coverage entirely, appraisal alone may not resolve the matter.
Why the Property’s Location Matters
Matching disputes are not decided by one rule that applies everywhere. The policy language, type of material, availability of a reasonable match, repair method, and state law all matter. A limitation in one policy may not appear in another.
What to Do If Your Insurer Cites Matching or Cosmetic Exclusions
If your insurer has cited a matching or cosmetic exclusion to limit or deny your claim, several steps are worth taking.
These steps include:
- Reviewing the exact policy language: Confirm the exclusion applies to your specific loss and that all conditions for its application have been met.
- Commissioning an independent assessment: A licensed contractor or engineer can document whether the damage has functional consequences beyond what the carrier has recognized.
- Checking applicable state law: Matching disputes are not resolved by a universal rule. The policy language, type of material, availability of a reasonable match, repair method, and state law all matter. A limitation in one policy may not appear in another, and a rule that applies in Florida may not apply in Colorado, Louisiana, or Texas.
- Invoking the appraisal clause: If the dispute is about the amount of the loss, invoking appraisal can move the matter to a neutral forum without litigation.
- Consider whether a state complaint is appropriate: Depending on the claim and jurisdiction, a policyholder may be able to ask the state insurance regulator to review how the claim was handled. Check policy deadlines first, and do not treat a regulatory complaint as a substitute for legal advice.
- Consulting an attorney: A property insurance claim dispute attorney can review the policy, the insurer’s coverage position, and applicable law to evaluate an effective path forward.
Frequently Asked Questions
The following are the most common questions about limited matching and cosmetic damage exclusions in property insurance claims.
What Is a Matching Exclusion in an Insurance Policy?
A matching limitation can restrict payment for undamaged areas when replacement materials do not reasonably match. Whether the insurer must address adjoining areas depends on the policy language, the material involved, the proposed repair, and the law that applies where the property is located.
Can an Insurance Company Deny Payment for Matching Shingles or Siding?
Yes, if the policy includes a limited matching exclusion and the undamaged materials remain functional, the insurer may decline to pay for matching replacement. Whether that position holds depends on the exact policy language, the facts of the loss, and applicable state law.
What Counts as Cosmetic Damage in an Insurance Claim?
Cosmetic damage is generally defined as damage affecting the appearance of property without impairing its ability to perform a protective function. A dented metal roof that still seals out weather, or impact-marked siding that remains structurally intact, may fall within a cosmetic damage exclusion. The correct characterization often depends on an independent engineering assessment.
How Do I Dispute a Matching Exclusion?
Start with the policy language to confirm the exclusion applies to your specific loss. Commission an independent contractor or engineer to document whether the damage has functional consequences. Review applicable state law, and consider invoking the appraisal clause if the disagreement concerns the amount of the loss rather than coverage itself.
Can the Appraisal Clause Help With a Matching Dispute?
Appraisal addresses the amount of a covered loss — it can help where the dispute concerns the cost of achieving a reasonable, uniform appearance after a partial repair. It does not resolve coverage questions. If the insurer’s position is that the matching exclusion eliminates coverage entirely, additional legal analysis is likely needed.
Are These Exclusions Enforceable in All States?
Enforceability depends on the specific policy language, how the exclusion was filed and approved by the state’s insurance department, and applicable state law. Florida, Louisiana, Colorado, and Texas each have distinct regulatory frameworks. An exclusion that is enforceable under one state’s standards may face challenge in another.
Speak with a Property Insurance Attorney About Your Claim
If your insurer has cited a limited matching exclusion, a cosmetic damage exclusion, or a combination of these provisions to limit or deny your claim, the coverage position you’ve received is worth reviewing. These provisions are not applied correctly in every claim, and the adjustment stage is not the end of the road.
At Kandell, Kandell & Petrie, we handle property insurance legal disputes exclusively and take over the entire process from the moment we are retained. That means carrier communications, document review, and representation through every stage. Clients receive direct access to the team handling their case, with clear benchmarks throughout the process.
To request a case review, contact our team at (305) 419-2649 and tell us about your claim.