May 31, 2026
Proof of Loss and Documentation Checklist: What Drives Property Insurance Claim Outcomes
Latest Post
Hurricane Isaias Property Damage: Next Steps for Your Claim
October 13, 2026
What Happens After an Insurance Claim Denial? A Step-by-Step Guide for Policyholders.
September 13, 2026
Resolve Before Litigation: Demand Letters, Notices of Intent, Mediation, and Appraisal in Insurance Disputes
September 13, 2026
When a claim is disputed, the documents often determine how clearly a policyholder can explain what happened, what was damaged, and what the repair should cost. A proof of loss is one formal part of that record. The complete claim file also includes the policy, photographs, estimates, invoices, reports, and carrier correspondence.
Commercial property owners, businesses, and condominium associations that document carefully, from the moment damage occurs through every interaction with the carrier, are in a fundamentally different position than those who try to reconstruct the record months later. Carriers know the difference. Their adjusters are trained to look for gaps in denied insurance claim documentation, and a thin file is an invitation to undervalue the loss.
This checklist covers what a complete claim file looks like, the documentation mistakes that quietly damage claims, and how to build a record that holds up at every stage of a dispute.
If your property insurance claim has been denied or the settlement falls short, contact Kandell, Kandell & Petrie at (305)-858-2220. We take over the entire process from the moment we are retained.
What Is a Proof of Loss?
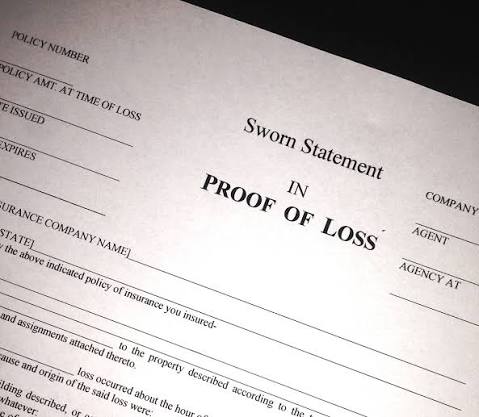
A proof of loss is a formal statement a policyholder submits to the insurance company describing what happened, what was damaged, and the amount being claimed. Depending on the policy and the form provided, it may need to be signed, sworn, or notarized.
The policy and the insurer’s written request determine when the proof of loss is due. Review both documents and the form itself before calculating the deadline.
The proof of loss is the official record that anchors your legal rights in the dispute process. Everything else in your claim file is the evidence that supports it.
Insurance Claim Documentation Checklist
The following items make up a complete claim file for a property insurance dispute. Not every item applies to every claim type, but the more thoroughly documented the file, the less room the carrier has to challenge scope or value.
Safety and reasonable mitigation come first. Take photographs and video when it is safe to do so, and do not delay emergency work solely to create a record. Save damaged materials when practical, document what must be removed, and ask the carrier in writing about inspection or disposal when time allows.
A complete claim file typically includes the following:
- Your policy and declarations page: The declarations page is a concise summary of your coverage, limits, and deductibles. Read it before the adjuster arrives. Know what is covered, what is excluded, and which provisions apply to your specific loss.
- The denial letter or adjuster’s estimate: If the claim has been denied or underpaid, this document defines the dispute. Every exclusion cited and every valuation the carrier has used is a potential pressure point in the dispute process.
- A written timeline of events: Document when damage occurred, when you first discovered it, when you reported to the carrier, and every substantive interaction after that. A clear claim timeline removes the carrier’s ability to argue delayed reporting or an ambiguous cause of loss.
- Photos and video evidence: Photograph damage before any mitigation or cleanup begins. Capture wide shots that establish context and close-ups that show specific damage in detail. Video walkthroughs are useful, as they narrate what you are seeing and when the footage was recorded.
- Contractor repair estimates: Contractor repair estimates: A detailed estimate from a qualified contractor can help identify differences in scope and pricing. Another estimate or expert opinion may be useful when the insurer disputes the repair method, cause, or amount, but the need depends on the claim.
- Receipts and invoices: Retain receipts for every repair expense, emergency service, and replacement item. If original receipts are unavailable, credit card statements, bank records, order confirmations, and warranty cards can serve as proof of ownership or payment.
- Mitigation and drying logs: For water damage claims, documentation of mitigation work (e.g., drying logs, moisture readings, equipment records) is critical. Carriers scrutinize this area closely, and gaps in the mitigation record are frequently used to question the scope of damage.
- A communications log: Record every conversation with the carrier, their adjuster, or any third party acting on their behalf. Write down the date, the name of the person you spoke with, and the substance of the call. Follow verbal conversations with an email confirming what was discussed.
- Independent assessments and third-party reports: Engineering assessments, public adjuster evaluations, and independent inspector reports can establish cause of loss, proper scope, or valuation where the carrier’s own adjuster has fallen short. If you are deciding who should help assemble or evaluate the claim record, compare the roles of a public adjuster and an attorney.
Common Documentation Mistakes That Hurt Claims
Documentation gaps can make it harder to establish when the damage occurred, what was affected, and what the repair should cost.
The following patterns appear regularly in the disputes we handle:
- Delayed reporting: Waiting too long to notify the carrier after damage occurs gives the insurer room to argue that the cause of loss cannot be verified or that damage worsened through neglect. Report damage as soon as it is discovered.
- No photos before mitigation begins: Once remediation work starts, the original damage record disappears. Photograph and video every affected area before contractors or restoration crews begin work. This is one of the most common and costly gaps in claim files.
- Discarding damaged materials too soon: Carriers and independent inspectors sometimes need to examine damaged materials directly. Structural elements, flooring, and equipment disposed of before the claim is fully resolved create evidentiary gaps the carrier will point to.
- A missing or vague timeline: Gaps in the timeline, such as undated photos, unconfirmed dates of discovery, no record of when the carrier was notified, invite the adjuster to fill those gaps in ways that work against you.
- Verbal-only communications with the carrier: Phone conversations with insurance company representatives are not a reliable record. Anything substantive discussed by phone should be confirmed in writing the same day.
How to Organize Your Claim File
A well-organized claim file moves faster through every stage of the dispute process and gives the carrier fewer grounds to claim missing documentation.
A simple folder structure is enough:
- Claim forms: Completed proof of loss forms and all related filings
- Communications and logs: Correspondence with the carrier, call logs, and email threads in chronological order
- Estimates and quotes: Contractor bids and itemized scope-of-work documents
- Financial records and receipts: Invoices, receipts, and bank or credit card records supporting claimed expenses
- Evidence: Photos, videos, and third-party reports
Name individual files using a consistent format. For example, MM-DD-YYYY_Description. This naming convention provides a clear timeline of the claim from the file names alone.
Scan paper receipts and physical documents. Back up the entire file to a secure cloud location and maintain a local copy. A claim file that can be retrieved, shared, and reviewed quickly is a meaningful advantage.
When Documentation Gaps Lead to Disputes
A claim that is well-documented going into the process carries more leverage at every stage, from the initial carrier dialogue through pre-suit demand, appraisal, and litigation if it comes to that. Carriers know when a file is thin.
When documentation has gaps (e.g., missing photos, an incomplete timeline, undocumented mitigation, or a communications record that exists only in memory), disputes become harder and outcomes typically reflect that. The appraisal process itself is built on documentation: appraisers on both sides rely on the documented record to assess valuation, and a well-built file gives your appraiser a stronger foundation to work from.
If your claim has already been denied or the settlement offer does not reflect the actual cost of your loss, the record you have built to this point matters.
Our team reviews what exists, identifies what can be supplemented, and opens direct dialogue with the carrier on your behalf. All communication with the carrier transfers to us from the moment of retention; you stop managing the process.
For further context on where a denied or underpaid claim goes from this point, see our pages on denied insurance claims, underpaid insurance claims, and property insurance claim disputes.
Sources and Authorities
The policy and any written request from the insurer control the proof of loss requirements for a specific claim. State specific statements below should link to the applicable legislature, insurance department, or court authority.
Frequently Asked Questions
The questions below address the most common documentation questions we hear from property owners and associations navigating a dispute with their insurer.
What Is a Proof of Loss?
A proof of loss is a formal statement that describes the cause of loss, the damage, and the amount claimed. Whether it must be signed, sworn, or notarized, and when it is due, depends on the policy and any written request from the insurer.
What Documents Do I Need for a Property Insurance Claim?
A complete claim file for a property insurance dispute typically includes your policy and declarations page, the signed proof of loss form, photos and video of the damage, a written timeline of events, contractor estimates, receipts and invoices, mitigation records, and a log of all communications with the carrier. The more complete and organized this file, the stronger the foundation for the dispute.
What If I Don’t Have Receipts for Damaged Property?
Receipts are preferable but not required in every situation. Credit card and bank statements, warranty cards, manufacturer records, home videos showing the property prior to the loss, and email order confirmations can all support a proof of ownership claim. Document what you have and note any gaps (alternative evidence can often fill them in a dispute).
Can a Claim Be Denied Because of Missing Proof of Loss Documentation?
Yes. Insurance carriers require documentation to establish the cause of loss, the scope of damage, and the value of what is being claimed. Incomplete documentation gives the insurer grounds to question the legitimacy or scope of the claim. Documentation gaps are one of the most consistent factors in partial payments and outright denials. An attorney reviewing the file can identify what is missing and assess whether the gap is recoverable.
How Is Documentation Used in the Appraisal Process?
When a claim dispute proceeds to the appraisal process, the documented record becomes the evidentiary foundation of both appraisers’ work. The scope of damage must be established based on the record, including photos, contractor estimates, mitigation logs, and third-party assessments. A well-built claim file gives your appraiser a much stronger foundation than a reconstructed one.
Does Documentation Matter Differently for Water Damage Claims?
Documentation carries particular weight in water damage insurance claims, hurricane and named storm claims, and any claim in which the carrier challenges the cause of loss or the scope of damage. In these situations, drying logs, moisture readings, and pre-mitigation photos are often the difference between an approved claim and a denied one. The timeline of discovery and response also comes under close scrutiny.
Speak with a Property Insurance Attorney About Your Claim
If your claim has been denied, underpaid, or stalled, and documentation gaps are part of the issue, a case review can clarify what the file shows, what can be supplemented, and where the dispute stands.
At Kandell, Kandell & Petrie, we exclusively handle property insurance legal disputes. From the moment we are retained, we take over all communication with the carrier. Our clients receive updates at defined stages; no chasing for status reports, no ambiguity about where the case stands. Litigation cases rarely last more than one year; many claims are resolved well before a lawsuit is ever filed.
Contact us at (305)-858-2220 to discuss your claim with a member of our team.